

Jim: sell & get paid instantly analysis by Appwee
Turning a phone into a payment terminal sounds simple, but the useful question is whether it makes everyday selling easier than carrying a separate card reader. I spent time looking at how Jim: sell & get paid instantly fits that job, and my overall impression is that it is aimed at people who want a lightweight way to accept card payments while moving around. It is a finance app from CloudWalk, available free of charge, with an Everyone age rating and support for devices running Android 7.0 or later.
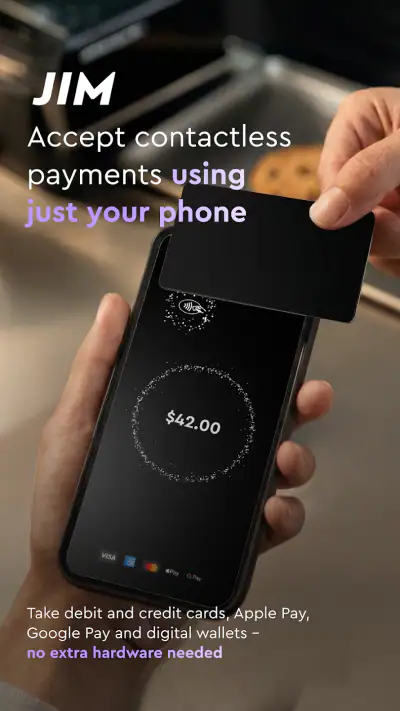
The concept is particularly appealing for independent sellers, mobile professionals, market-stall operators, and anyone who occasionally needs to take a payment away from a fixed checkout. Instead of treating a phone as only a place to manage money, Jim makes it part of the transaction itself. That can remove one item from a work bag and make spontaneous sales more practical.
How Jim works in real selling situations
The strongest part of Jim: sell & get paid instantly is its clear focus. It is not presented as a general budgeting tool, investment service, or banking replacement. Its role is to help a seller use a phone as a card reader and receive payment quickly. That narrow purpose makes the app easier to understand than finance apps that try to cover every possible money task at once.
A realistic example would be a freelance photographer finishing a small event and needing to collect a remaining balance before leaving. With a conventional setup, the photographer might need to carry a separate terminal, keep it charged, remember its connection method, and check that it is ready before the appointment. A phone-based option can be more convenient when the business is already being run from that phone.
The same idea works for a craft seller meeting a customer, a beauty professional visiting clients, or a small service provider who does not operate from a permanent counter. In these cases, the value is not just speed. It is the reduction of equipment and preparation. The phone is already likely to be nearby, so the payment process can fit into an existing routine rather than requiring a second device.
I also like the fact that the app’s purpose is understandable before installation. The store summary describes selling anywhere and getting paid in seconds, which gives a prospective user a useful picture of the intended experience without burying the main function under financial jargon. That clarity matters when a seller needs to decide quickly whether an app belongs in a business workflow.
There is an important distinction, though: a phone becoming a card reader does not automatically mean it replaces every part of a full point-of-sale system. A larger retail operation may still need inventory control, printed receipts, staff accounts, detailed reporting, refunds, tax workflows, or integrations with other business tools. Jim makes the most sense when accepting the payment is the central need, not when the payment is only one small part of a complex retail operation.
What the free price means for its value
Jim is listed as free, so the initial decision is straightforward: installing it does not require buying the app. That makes it easier to test whether a phone-based reader suits a particular type of selling. For someone who only accepts payments occasionally, avoiding an upfront app purchase can be meaningful because the tool can be considered without committing money before the first use.
Free access should still be judged by practical usefulness rather than by the price label alone. A seller needs to consider the complete payment setup, including the phone, connectivity, account arrangements, and any transaction-related terms that apply during actual use. Those details affect the real cost of accepting payments, so I would review them carefully before relying on the app for a busy sales day.
That is also why I would not describe Jim as automatically cheaper than every physical reader or competing service. The app itself is free, but the overall value depends on how often it is used and what the seller already owns. Someone who has a reliable terminal and a mature checkout process may gain little from changing. Someone starting with only a compatible phone may find the low entry barrier much more attractive.
The app’s current version is 1.4.19, and its presence on the store suggests an established enough product for people to investigate rather than a purely theoretical payment idea. It has an average rating of 4.4 from around two thousand ratings, along with more than four hundred written reviews. Those figures indicate useful user interest, but they should not replace testing the app with a small transaction first, especially when payment reliability matters.
Small workflow choices that make a difference
My first practical tip is to prepare before meeting a customer. A phone-based payment tool is only helpful if the phone has enough battery, the app opens normally, and the seller knows where to look when a payment is complete. A short test run in a quiet setting is more valuable than discovering a setup problem while a queue is waiting.
Second, I would keep a backup payment plan. This is not a criticism unique to Jim; any mobile payment method can be affected by a flat battery, poor connectivity, device trouble, or a customer’s card issue. A seller who carries a second accepted payment method, or at least knows how to record an unpaid order clearly, avoids turning a technical interruption into a confused customer experience.
Third, I would separate the payment moment from the record-keeping moment. Jim’s central job is accepting money, but a seller may still need to note what was sold, who bought it, and whether the payment belongs to a deposit or a final balance. Keeping a simple sales log alongside the app can prevent the common mistake of assuming that a successful payment screen is the same thing as complete business bookkeeping.
A fourth useful habit is to use a consistent confirmation routine. After a customer pays, I would check the result in the app, state clearly that the payment has gone through, and then record the sale immediately. That small sequence helps when several customers pay one after another and reduces the chance of mixing up a completed transaction with an abandoned attempt.
Where the trade-offs appear
The convenience of using a phone also creates dependence on that phone. If the device is being used for calls, navigation, stock notes, or customer messages, a payment interruption can affect several parts of the business at once. A dedicated terminal is less flexible, but it can keep payment activity separate from the seller’s personal device.
There is also a learning curve for customers. Many people understand a traditional card reader instantly because they have used one in shops. A phone acting as the reader may require the seller to explain where to tap or how to position a card. That explanation may be brief, but it becomes more noticeable when the seller is serving several people quickly.
I would also be cautious about treating “paid instantly” as a promise that every part of the money journey is immediate in every circumstance. The phrase communicates the intended experience, but payment confirmation, settlement, and access to funds are not always identical concepts. Before making cash-flow plans around the app, a business owner should understand the relevant account and transaction conditions for their situation.
Another trade-off is physical confidence. Some customers feel more comfortable with a familiar terminal, especially when paying a larger amount. A phone can look informal even when the process is legitimate. The seller can offset that impression by explaining the amount clearly, showing the confirmation screen when appropriate, and keeping the transaction process calm and transparent.
Jim may also be a poor fit for businesses that need a broad operational system. If the main challenge is stock management, employee permissions, detailed sales analytics, or complicated receipts, a complete point-of-sale platform will probably offer more value. Jim’s focused approach is a strength for mobile selling, but it is not a substitute for every business tool.
Who is likely to get the most value?
I see the clearest match with people who sell in changing locations. A market vendor can use the app when customers do not carry cash. A tutor or repair specialist can accept a payment at the end of a visit. A small event seller can avoid bringing a separate reader when the phone is already part of the setup. In each case, the app’s value comes from portability and a short path between agreeing a sale and completing it.
It can also suit a new seller who wants to validate an idea before investing in more equipment. Because the app is free to download, the person can explore whether mobile card acceptance fits the business routine. I would still begin with low-pressure transactions, learn the process, and confirm how the financial side works before advertising card payments as the only option.
Occasional sellers may benefit more than high-volume stores. Someone selling a few items at irregular intervals may not want to maintain a dedicated terminal. The phone-based approach can be easier to keep available, provided the seller is comfortable with the device requirements and has a backup plan.
On the other hand, I would skip Jim if a business already depends on a fixed checkout with integrated inventory, staff controls, and detailed reporting. I would also hesitate if mobile connectivity is unreliable at the places where sales happen, or if the seller cannot keep the phone charged and available. In those situations, a dedicated reader or a complete point-of-sale package may be the more dependable choice even if it is less portable.
Customers who are especially concerned about payment security should take time to understand the app’s normal process and use the latest available version. The Everyone rating makes it broadly accessible from an age-classification perspective, but that label does not answer every practical question a business owner may have about account security, transaction handling, or support. Those are worth checking before making Jim central to daily revenue collection.
How it compares with the usual alternatives
Compared with cash, Jim offers a way to accept card payments without asking every customer to carry notes and coins. That can reduce missed sales when a buyer has no cash available. Cash remains useful as a backup because it does not depend on a phone battery or a mobile connection, so I would not remove it from the contingency plan too quickly.
Compared with a traditional card reader, Jim’s main advantage is reduced hardware. A separate terminal can feel more professional and may be better suited to repeated transactions, but it adds another device to charge, transport, and maintain. The right choice depends on whether portability or dedicated reliability matters more in the seller’s environment.
Compared with a full point-of-sale app, Jim appears more focused on the payment action itself. That simplicity can be welcome when a freelancer wants to finish a sale without navigating a large system. It becomes a limitation when the business needs payment acceptance tied to stock, customer records, employee activity, or extensive reporting.
Compared with bank transfer requests or payment links, a card-reader workflow can feel more immediate during face-to-face selling. A transfer may be convenient for some customers, but it can introduce waiting, account-entry mistakes, or uncertainty about whether the money has arrived. Jim’s appeal is strongest when the buyer and seller are together and the seller wants a direct payment interaction.
My verdict for everyday use
After weighing the free access against the practical trade-offs, I think Jim is worth trying for mobile sellers who want to accept card payments with less equipment. Its strongest use case is not a large shop with a complicated checkout; it is the independent seller, service provider, or occasional trader who needs a compact way to take payment while working away from a counter.
I would install it before an upcoming selling day, test the workflow, prepare a backup method, and make sure the phone is ready for uninterrupted use. I would also read the current transaction and account terms carefully, because the app’s free price does not by itself describe the complete cost of payment acceptance.
CloudWalk has made a focused finance tool rather than an all-purpose business suite. That focus is both the reason to choose it and the reason not to expect it to solve inventory, accounting, or retail-management problems. For the right user, the ability to turn an existing phone into a payment point can be genuinely useful.
My recommendation is therefore positive but specific: choose Jim if portability, a free starting point, and straightforward card acceptance matter most. Skip it in favor of a dedicated reader or broader point-of-sale system if your business needs a full operational backbone. With that distinction in mind, the real value is convenience without an upfront app price, not a promise that one phone can replace every business tool.
Gallery
Jim: sell & get paid instantly Pros and Cons
- Create listings quickly with photos
- descriptions
- and prices.
- Instant payment options can speed up completed sales.
- Useful marketplace tools help manage multiple listings.
- Chat features make it easier to communicate with interested buyers.
- Simple interface is approachable for occasional sellers.
- Availability of payment features may vary by country or region.
- Seller fees can reduce the final amount you receive.
- You may need to handle shipping
- pickup
- or delivery yourself.
- Buyer interest and sales speed can vary significantly by location.
- Scams and unreliable buyers remain possible on any marketplace.
Jim: sell & get paid instantly Frequently Asked Questions
What is Jim: sell & get paid instantly?
Jim: sell & get paid instantly is a marketplace app designed to help users list items for sale, communicate with potential buyers, and receive payment through the platform. It is intended to make local or direct selling more convenient by bringing listings, buyer interactions, and transaction-related features into one mobile experience. Availability and specific functions may vary by country.
How do I sell an item using the Jim app?
To sell an item, you generally create an account, add photos and a description, choose a category, set your price, and publish the listing. Clear images and accurate information can make your post more attractive to buyers. Before confirming a sale, review the buyer details, payment status, delivery or collection arrangements, and any fees shown in the app.
Do I really get paid instantly after selling something?
The phrase “get paid instantly” refers to the app’s payment experience, but the exact timing can depend on the payment method, transaction verification, bank processing, account status, and local availability. Some payments may be subject to review, withdrawal limits, or temporary holds. Always check the current payment terms inside the app before relying on immediate access to funds.
Is Jim safe to use for buying and selling?
Jim may provide features intended to support safer transactions, such as user accounts, in-app communication, and payment handling, but no marketplace can eliminate every risk. Avoid sharing passwords or sensitive financial information in messages, verify item details before paying, and be cautious of requests to move conversations outside the platform. Meet locally only in public places when appropriate.
Are there fees or requirements for using Jim?
Using Jim may involve account requirements, identity or payment verification, listing rules, transaction charges, withdrawal fees, or other costs depending on the service and your location. Some features may also be restricted by age, country, or payment-provider availability. Before publishing an item or accepting an offer, carefully review the price breakdown, terms, cancellation rules, and payout conditions displayed in the app.














